UK diesel spot price hits new high, energy futures show signs of strengthening
The US-Iran conflict is disrupting the world's oil supply system and the UK diesel spot price has hit a record high.
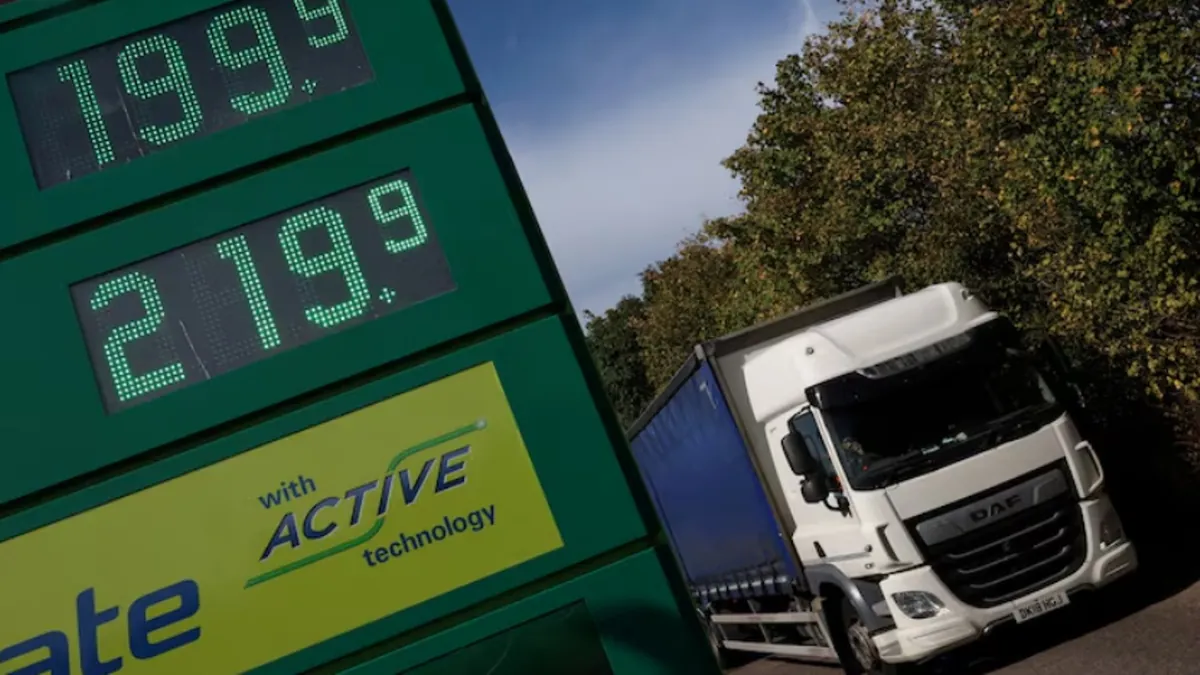
UK diesel spot price breaks historical high.
Tensions between the US and Israel about Iran, including military clashes, keep putting steady pressure on the world's oil supply system. The spot price for diesel in the UK has hit a record high. Diesel prices in the UK have risen to over 199.18 pence a liter, data shows, surpassing the previous high seen during the Russia-Ukraine energy crisis in 2022. It cost £31 more than before the war to fill a tank of diesel for an ordinary family car and the total cost of a single fill-up was almost £110.
The soaring cost of terminal fuel has not only increased the burden on people's lives but also raised the logistics costs throughout the entire industry chain. As diesel is the core fuel for industry, agriculture, and land transportation, its price increase will be passed on layer by layer to various links such as commodity transportation and production processing. This is also an important reason for the recent resurgence of inflation in the UK, with the inflation data in August reaching a five-month high and the pressure on living costs intensifying.
The domestic refining capacity has shrunk, and rumors of an export ban in the US are spreading.
The UK once had 6 refineries operating at a rate of 1.27 million barrels per day of crude oil. Last year, two refineries were officially closed due to capacity updates and only four refineries are currently in operation, processing 1 million barrels daily. The domestic crude oil refining capacity has largely declined. The capacity gap can only be filled by imports, and the UK's dependence on diesel imports has increased.
The latest energy data shows that diesel imports account for 55% of its domestic total consumption, and the overall share of oil product imports, with diesel accounting for nearly 40%. Among them, the United States is the core import source, contributing 31% of the total imports. The supply structure that is highly dependent on imports has completely exposed the UK's diesel market to global risks.
The biggest uncertainty in the energy market recently comes from the change in the policy direction of the United States. It has been reported that the United States is considering banning the export of domestic diesel, casting a shadow over the global refined oil market. The United States is an important diesel exporter in the world and also the core oil supply source for the UK. Once the export ban takes effect, the UK will be forced to seek alternative sources in the global market. Now, global diesel is already in a state of insufficient supply, and the new procurement demand will further exacerbate the supply-demand contradiction.
Global refining capacity is tight, and there is still room for the market to rise.
Over the past few months, the overall global refining capacity has been relatively tight. Coupled with the ongoing geopolitical conflicts in the Middle East and Russia-Ukraine, the transportation and production of refined oil have been restricted. The war in the Middle East has affected shipping in the Strait of Hormuz, blocking the transportation of crude oil, and restricting the supply of raw materials to refineries. The conflict in Russia-Ukraine has further reduced the global diesel output. The combination of these factors has led to a continuous low level of global diesel inventories and a severely insufficient buffer space.
By comparing the oil prices in several European countries, it can be seen that although the diesel price in the UK has reached a new high, it is not at the top of Europe. Currently, the diesel price in the UK ranks seventh among the 15 European countries, and it is the same as that in Italy. The diesel prices in Germany, France and other countries are all higher than that in the UK. There is still room for the diesel price in the UK to rise.
Industry institutions indicate that there is a lag in the terminal fuel prices. Only when the international oil prices fall for several weeks can the terminal prices be driven down. The short-term geopolitical risks are still ongoing, and it is difficult for oil prices to fall rapidly. The strong trend of diesel futures will continue.